idxrosemarie63
About idxrosemarie63
This is the science behind A perfect Housing
There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
 In markets where builders have added meaningful supply in recent years, prices have pulled back. Phoenix, Austin, and parts of Florida saw corrections of ten to fifteen percent from peak levels in some submarkets. But those are the exceptions. Most markets are not working from excess; they are working from scarcity.

 Shop at least three lenders before you commit to one. A seemingly small rate difference adds up to real money that most buyers leave on the table by taking the first offer they receive. Lender fees vary too. Ask each lender for a Loan Estimate document, which breaks down all costs in a standardized format.
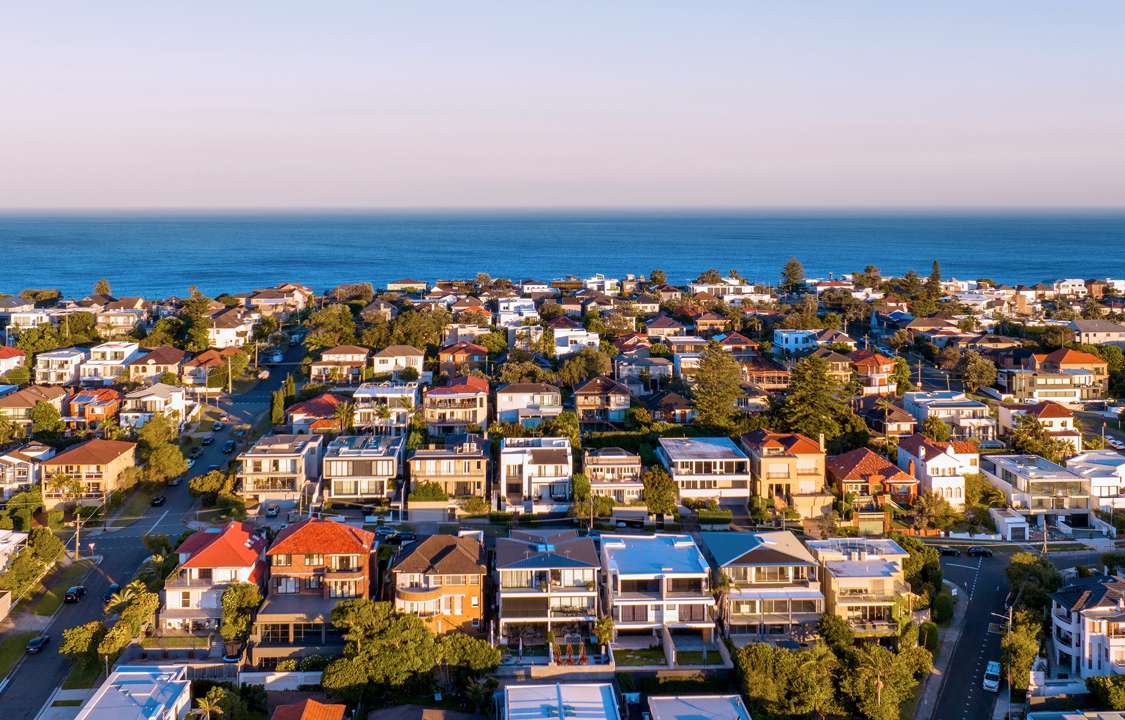 The appraisal is the lender’s check, not yours. When the appraisal comes in below contract, the deal does not automatically die, but it does require a decision. Ask your agent what the local pattern looks like before you structure an offer without an appraisal contingency.
Negotiation works best when it is quiet and well-prepared. Before you make an offer, find out how long the listing has been active. A listing with a history of two failed deals in the past month is a fundamentally different negotiation than a fresh listing in a neighborhood where homes sell in under a week.
 The timing question, whether to buy now or wait for prices to pull back, is the one that trips up more buyers than any other single factor. Waiting for the perfect moment is how people end up renting for another five years when they did not mean to. The more useful question is not whether now is the right time in the abstract; it is whether the home works for your actual life for the next five to seven years.
 Buyers who take the time to prepare before they start looking tend to find that opportunities exist even when conditions look difficult on paper. Spending twenty minutes with current homes for sale and market analytics is a better use of your time than waiting for conditions that may never arrive.
No listing found.